The deductible is the part of a covered repair bill you pay before insurance pays the rest. Here is how it works, where it applies, and what changing it does to your premium.
Car insurance comes with two costs that are easy to mix up. The premium is what you pay to keep the policy active, usually each month or every six months. The deductible is the share of a covered repair bill that comes out of your own pocket before your insurer covers the rest. Knowing how the two fit together makes it easier to pick an amount you can live with.
What a Deductible Is, and What It Is Not
A deductible is your fixed share of a covered loss. The policy sets the amount, and the insurer pays only the portion above it. A few points keep the definition clear:
- It is not an annual total. Auto policies generally do not make you meet a yearly deductible. You pay the amount each time you file a claim, with some exceptions.
- It does not apply to every expense. Only covered costs count. If something falls outside the policy, it cannot be applied toward the deductible.
- It is not always charged. When another driver causes the crash and their insurer accepts responsibility, their policy may pay for your repairs and you may owe nothing.
Deductibles generally reset each policy period. Some policies calculate the deductible as a percentage of the claim cost instead of a flat dollar amount, so check your paperwork to see which setup you have.
Where Deductibles Apply
An auto policy bundles several coverages, and deductibles attach to some but not all:
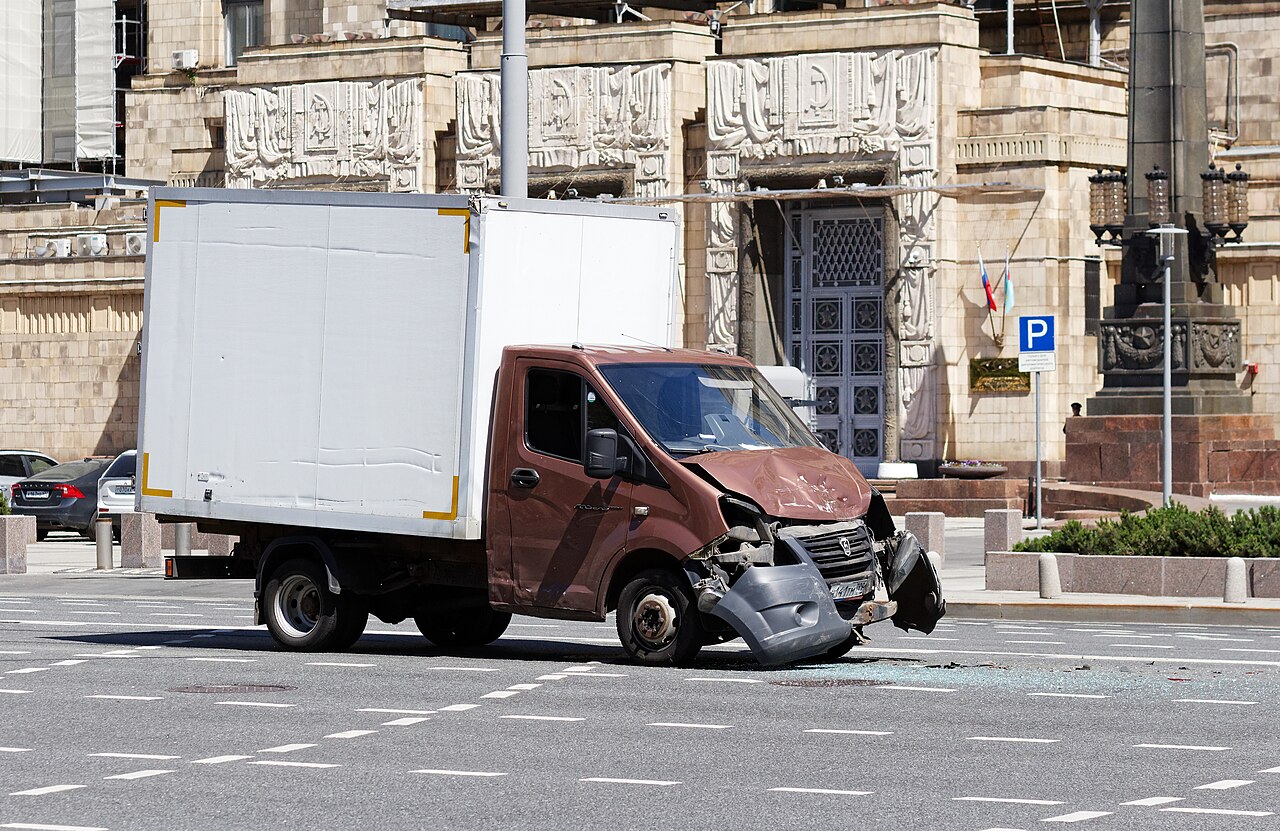
- Collision coverage pays to repair or replace your car after a crash with another vehicle or an object. It usually carries a deductible.
- Comprehensive coverage pays for damage from events other than crashes, such as theft, weather, or hitting a deer. It usually has its own deductible, often a different amount from the collision one.
- Liability coverage pays for damage or injuries you cause to other people. Liability insurance may have no deductible at all.
- Coverage for damage caused by a driver with no insurance, and coverage for your own medical costs after a crash, can carry deductibles as well.
These coverages are common. A Triple-I analysis of 2023 data from the National Association of Insurance Commissioners found that 80 percent of insured drivers buy comprehensive coverage on top of liability, and 77 percent buy collision.
A Worked Example
The following numbers are an illustration, not a quote. Say you have comprehensive coverage with a $500 deductible and your car takes $3,000 in damage from hitting a deer. You would pay $500 and your insurer would pay the remaining $2,500. With a $1,000 deductible instead, you would pay $1,000 and the insurer would pay $2,000.
How the money moves matters too. Most of the time you pay your share at the repair shop, and the insurer covers the balance. If the car is totaled, the insurer often removes your deductible from the settlement amount instead.
Higher Deductible, Lower Premium: The Trade-Off
The deductible and the premium move in opposite directions. A low deductible pushes the rate up, and a high deductible pulls it down, because a higher deductible means you have agreed to absorb more of each loss yourself.
The savings can be meaningful. According to Triple-I, moving a deductible from $200 to $500 could cut collision and comprehensive costs by 15 to 30 percent, and a $1,000 deductible can save 40 percent or more. Exact figures depend on the insurer, so collect quotes at several deductible levels to see your own numbers.
The stakes are real because car insurance is a large line item for many households. The countrywide average auto insurance expenditure rose 14.0 percent to $1,282 in 2023 from $1,127 in 2022, according to the National Association of Insurance Commissioners.
| Your choice | Premium | Cost when you file a claim |
|---|---|---|
| Lower deductible | Higher | Less out of pocket |
| Higher deductible | Lower | More out of pocket |
When a High Deductible Backfires
A deductible saves money only if you can pay it. If a claim comes and your share is out of reach, the repair may sit unfinished, or the gap may get filled with borrowed money that costs more than the premium savings ever added up to.
Remember that a deductible applies per claim, not per year. With some exceptions, each loss you file comes with its own deductible, so two accidents in one policy period means paying it twice.
There is also a point where coverage stops making sense at all. Triple-I suggests reviewing the coverage on older cars: when the car’s value falls below ten times what the coverage costs, keeping collision and comprehensive may not be worth the price. Dropping them ends the deductible question entirely, though it leaves repair bills in your hands.
Heads up: Before raising your deductible, check that your savings could cover the full amount on short notice. Triple-I lists this as the first condition for the savings, and it applies to every driver.
Picking an Amount You Could Actually Pay
- Look at your savings and pick a deductible you could cover today without borrowing or a payment plan.
- Get quotes at two or three deductible amounts and compare the premium difference.
- Read the quote or policy documents, which list the deductible separately for each coverage that has one.
- Ask about waivers. Windshield glass repairs under comprehensive coverage are often waived, and some states offer options that remove the deductible in specific situations.
Rules and options vary by state, so your state insurance department is a useful source for what applies where you live. For decisions about your own policy, an agent or a qualified professional can walk through the numbers with you.
Building a deductible fund is a savings goal like any other. Our guide to round-up savings looks at whether spare change really adds up, and saving on a tight budget covers what to do when almost nothing is left over each month. If you need room in the budget for that fund, cutting a recurring bill is a quick start, as in our piece on cheaper phone plans.
Quick wins
- A deductible is the amount you pay toward a covered loss before your insurer pays the rest of the claim.
- Collision and comprehensive coverage typically carry deductibles; liability coverage usually does not.
- You pay a deductible each time you file a claim, not once a year, and only on expenses the policy covers.
- Raising a deductible from $200 to $500 could cut collision and comprehensive costs by 15 to 30 percent, according to Triple-I.
- Choose a deductible you could pay out of pocket today without borrowing.
You might be wondering
Do I pay a car insurance deductible every year?
No. Auto policies generally do not have an annual deductible to meet. You pay a deductible each time you file a claim, with some exceptions, and it typically resets each policy period.
Does liability coverage have a deductible?
Usually not. Liability insurance, which pays for damage or injuries you cause to others, may not have a deductible at all. Deductibles typically attach to collision, comprehensive, coverage for damage from uninsured drivers, and personal injury protection, which covers medical costs after a crash.
Can my deductible ever be waived?
Sometimes. Windshield glass repairs under comprehensive coverage are commonly waived, and some states offer coverage options that eliminate the deductible in specific scenarios. If the other driver is at fault and their insurer accepts liability, their policy may pay for your damages and you may owe nothing.
How do I find the deductible amount on my policy?
Look at your policy documents or declarations page, where the deductible is listed separately for each coverage that has one. Quotes should show it too, so compare the same deductible amount across insurers.
These tips are general information. Prices, plans and programs vary by provider and location, so check the details with your provider before you switch or sign up.